The mortgage payment is only one part of owning a home. A useful Central Oregon budget also accounts for taxes, insurance, utilities, maintenance, association obligations, rural systems, seasonal work and the cash needed after closing.
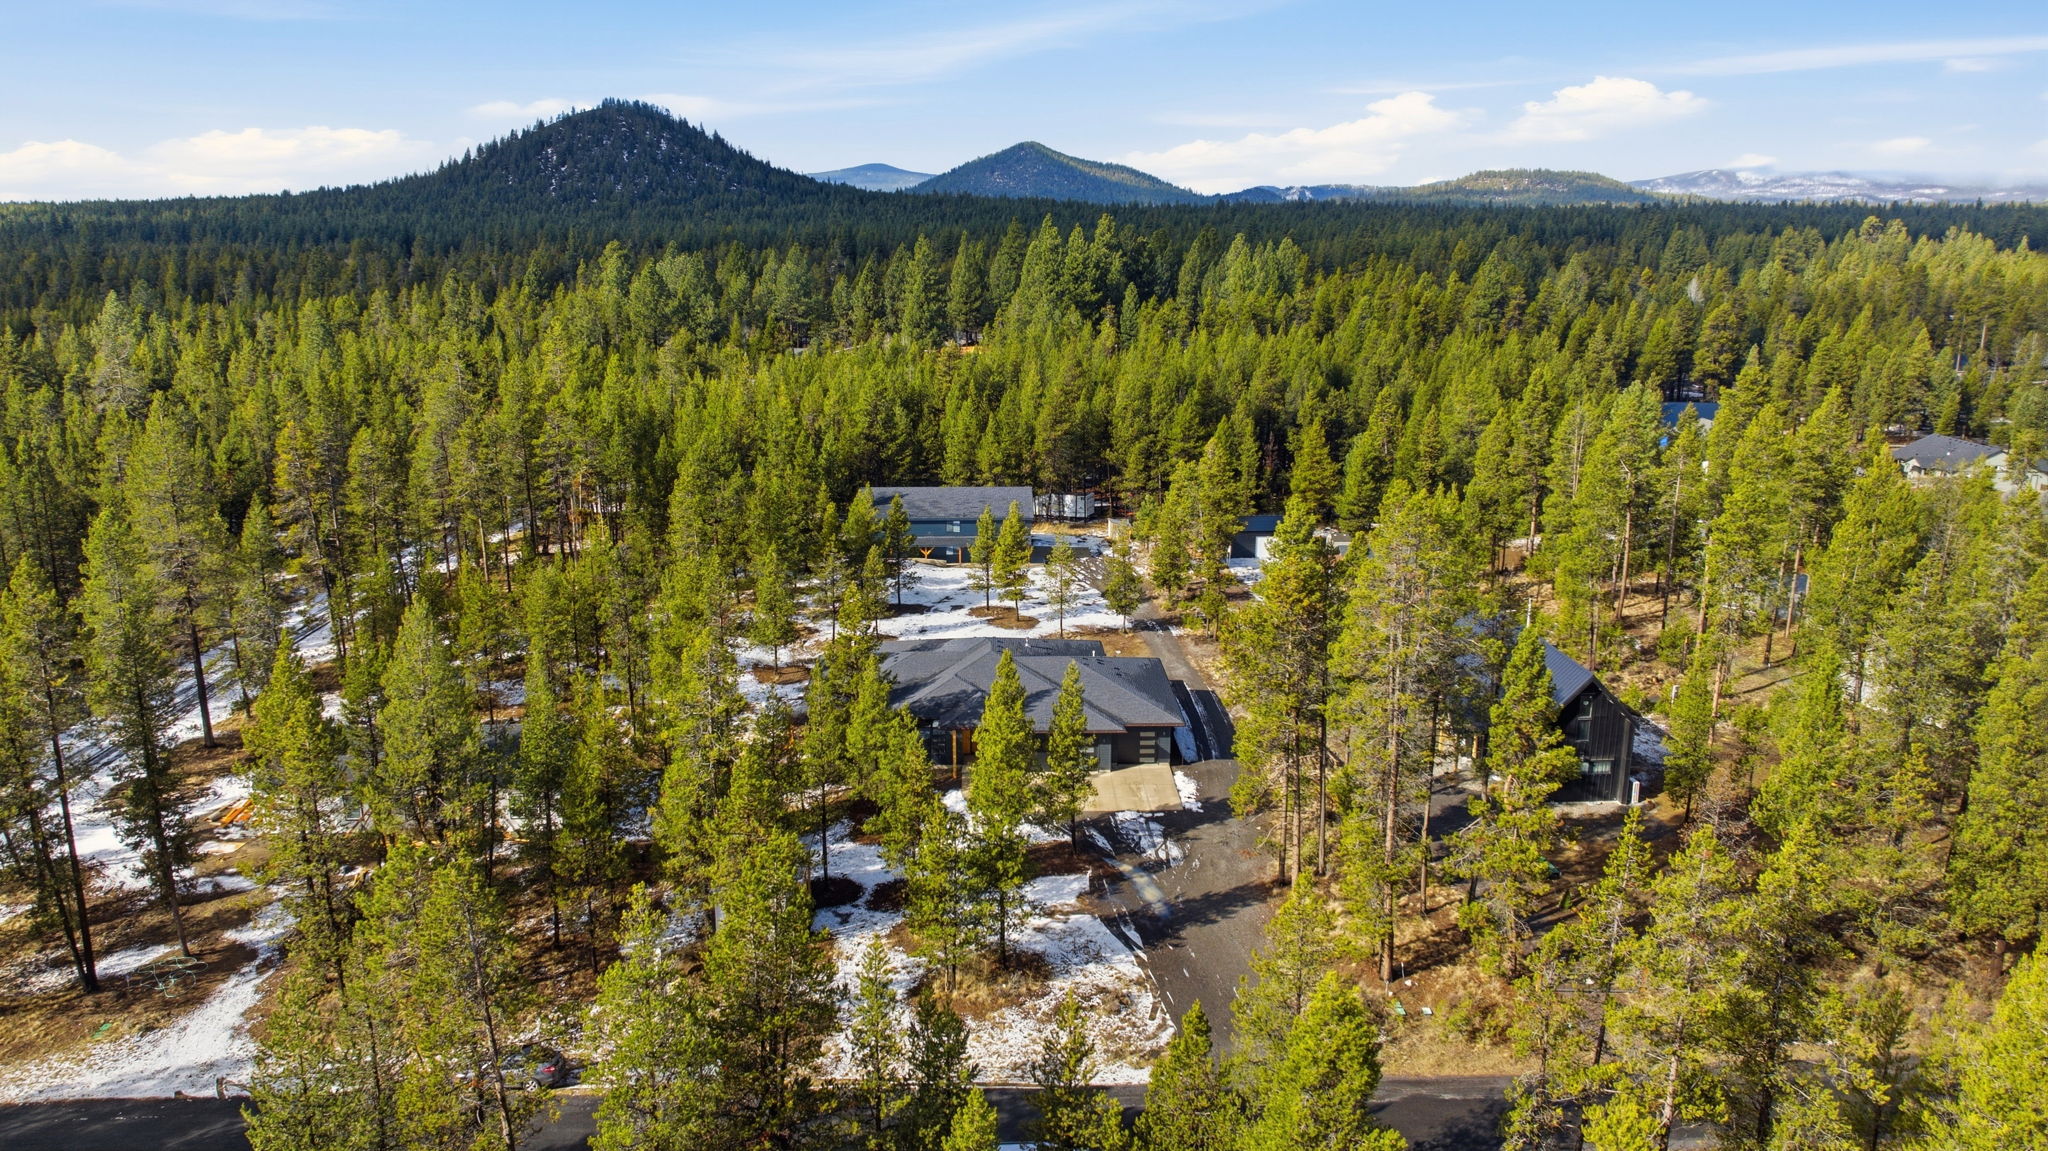
These costs are property-specific. A newer Bend townhome, an older west-side house and a rural acreage property can have very different operating and replacement needs even at the same purchase price.
Separate the budget into three buckets
- Monthly or quarterly costs: loan payment, utilities, insurance, taxes collected through escrow, HOA dues and routine services.
- Annual or seasonal costs: irrigation, landscaping, chimney or HVAC service, snow work, pest control and vacation-home monitoring.
- Repair and replacement reserves: cash set aside for components such as the roof, exterior, heating and cooling, appliances, well, septic system, driveway or private road.
This structure is more useful than applying one generic percentage to every property. The reserve should reflect the home’s age, condition, systems and inspection findings.
Property taxes: use the actual parcel
Review the current tax statement, assessed value, exemptions and tax history for the property. Deschutes County DIAL provides parcel and tax information, and the county’s tax estimator can help explore a specific account.
Do not assume the seller’s current bill is a perfect forecast. Ask about pending changes, omitted improvements, special assessments or tax programs that could affect the property after transfer. Escrow and the county can explain how the current account will be handled; tax advice should come from a qualified tax professional.
Homeowners insurance: quote the property before closing
Premium and availability depend on the home, coverage limits, deductible, claims information, replacement cost and insurer underwriting. Wildfire exposure can be material in Central Oregon, but a map or neighborhood label is not an insurance quote.
Obtain a property-specific quote early enough to resolve eligibility, premium and deductible questions during due diligence. The Oregon Division of Financial Regulation provides wildfire and home-insurance guidance and consumer assistance.
Also ask whether separate coverage or endorsements may be needed for flood, sewer or drain backup, equipment, valuables, a home business, short-term rental use or other circumstances relevant to the property.
Utilities: verify providers, systems and recent use
Identify how the home is heated and cooled and who provides electricity, gas or propane, water, sewer, garbage and internet. Request recent bills when available, but treat them as one household’s history rather than a guarantee of future cost.
Consider square footage, insulation, windows, HVAC age, thermostat habits, hot-tub or pool equipment, irrigation, electric-vehicle charging and occupancy pattern. For a rural property, include propane delivery, well-pump electricity, water treatment and internet equipment.
Maintenance and replacement: build from the inspection
A home inspection is a snapshot, not a warranty. Use it with seller disclosures, permits, invoices and specialist evaluations to create a component list:
- estimated age and condition;
- expected service interval;
- likely repair or replacement scope;
- rough cost range from an appropriate contractor; and
- the year in which you may need the cash.
Prioritize safety, water management, roof and exterior, heating, cooling, electrical, plumbing and structural concerns. Cosmetic projects can then be considered without crowding out essential reserves.
HOA dues and special assessments
For a condominium or planned community, review the declaration, bylaws, current budget, reserve information, insurance, meeting minutes, pending projects, owner balance and any announced assessment. Oregon’s Planned Community Act addresses association records, reserves, assessments and related obligations, but the governing documents and facts of the specific association still matter.
Monthly dues may cover services you would otherwise pay directly. The better question is not simply whether the fee is high or low, but what it covers and whether the association appears prepared for foreseeable expenses.
Rural systems can shift costs from a utility to the owner
On acreage and unincorporated properties, investigate:
- private or shared well operation, testing, pumps, storage and treatment;
- septic type, age, permits, inspection and maintenance history;
- private-road agreements, snow removal and surface maintenance;
- irrigation rights, delivery infrastructure and seasonal obligations;
- propane tank ownership or lease terms;
- outbuildings, gates, fencing and vegetation management; and
- internet, generator or backup-power needs.
Oregon Health Authority maintains domestic-well safety resources, and Oregon DEQ recommends inspection and maintenance planning for septic systems. For shared water, use the separate shared-well buyer guide.
Move-in and ownership costs that do not appear on the loan estimate
Cash needs after closing may include locks, window coverings, appliances, furniture, storage, landscaping tools, immediate repairs, moving, deposits and temporary housing. If the home will be vacant or used part time, add monitoring, winterization, snow service and travel.
Keep these items separate from lender closing costs. A lender’s cash-to-close figure does not represent the full first-year ownership budget.
A practical pre-offer worksheet
| Category | Documents or quotes to collect |
|---|---|
| Taxes | Current statement, DIAL record, known assessments |
| Insurance | Property-specific quote, coverage and deductible |
| Utilities | Providers, recent bills, system type and age |
| Maintenance | Inspection, disclosures, permits and service records |
| HOA | Budget, reserves, minutes, insurance and assessments |
| Rural systems | Well, septic, road, irrigation and propane records |
| Move-in | Immediate repairs, equipment, moving and setup |
| Emergency reserve | Cash available after down payment and closing |
Test the budget before choosing the house
Run a normal-year scenario and a repair-year scenario. The second should include at least one plausible major expense identified during due diligence. If that scenario leaves no room for savings or ordinary life, adjust the price range, down payment, property type or timing before the purchase becomes urgent.
The Bend first-time buyer guide can help organize financing and offer preparation. For a property-specific ownership-cost review, contact Bend Relo before writing the offer so the right records and inspections can be built into the plan.
Talk with David & the Bend Relo team
Buying, selling, relocating, or evaluating a specific property? Tell us what you are working through. We are happy to help.