There is no single Bend home-buying timeline. A financed city-home purchase, a cash offer on acreage and a new-construction contract can move at very different speeds. The useful timeline is the one written into your offer, coordinated with your lender and expanded to include the property-specific work you need before becoming committed.
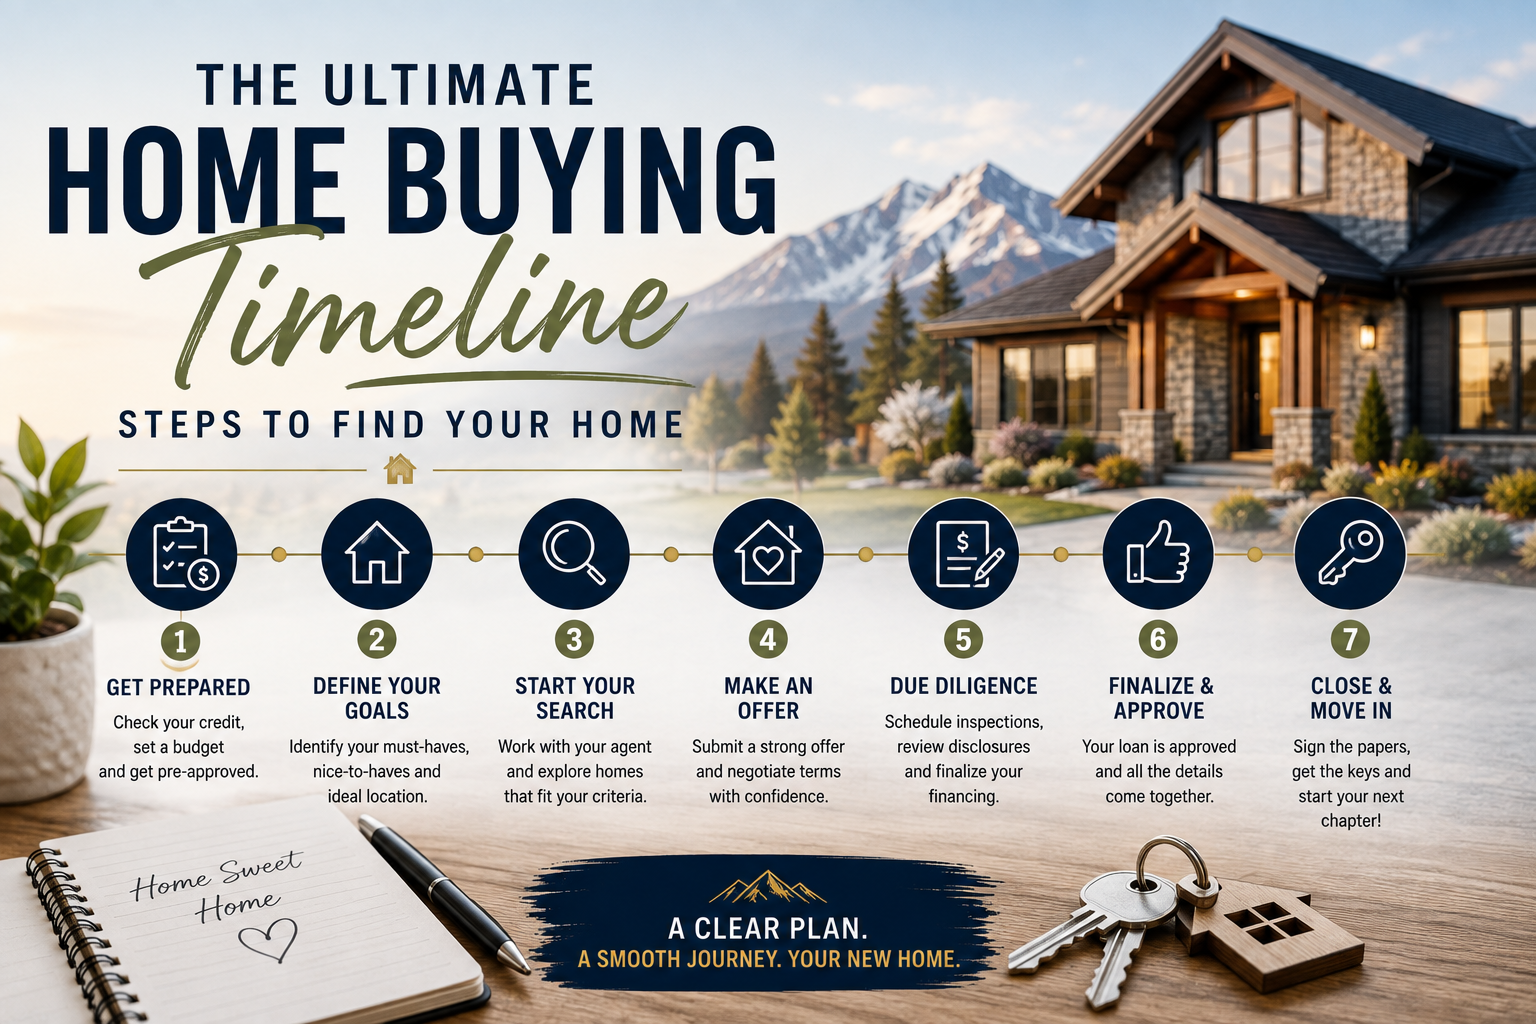
The sequence is more important than a generic number of days: prepare the financing and decision criteria, learn the areas, write an offer with deliberate terms, complete due diligence, finish the loan and title work, review final documents, then close and take possession as the contract provides.
Before touring seriously: define the decision
Start with the way you expect to use the property. A relocation buyer comparing Bend neighborhoods needs different information from someone seeking a rural shop, short commute, multigenerational space, future ADU or low-maintenance second home.
Write down the non-negotiables and the tradeoffs you can accept. In Central Oregon, that may include winter access, wildfire exposure, insurance availability, private-road obligations, wells and septic, HOA rules, topography, sun and snow patterns, or proximity to the routes and services you actually use.
David Keyte’s buyer due-diligence approach is to identify the intended use first, then determine what needs verification. A buyer can love a home and still need to slow down long enough to investigate the expensive systems, land-use constraints and location questions that could change the decision.
Get financing ready before the right home appears
If you will use a mortgage, speak with a lender before treating a listing as an option. A useful pre-approval is based on reviewed financial information and a realistic discussion of payment, cash to close and reserves—not only the maximum price a calculator produces.
Ask what documentation will need updating, how quickly the lender can respond when you write an offer and which property types could require additional review. Condos, manufactured homes, acreage, income property and homes with unusual features may not follow the same underwriting path as a typical detached house.
Keep the financing work current while you search. Avoid opening new credit, moving large sums without documentation or making other financial changes without first discussing the effect with the lender. Our mortgage pre-approval guide explains the questions worth asking before an offer.
Learn the area through your daily routine
Online research can narrow the map, but it cannot reproduce a Tuesday commute, a winter approach road or the difference between living near an amenity and using it regularly. Visit promising areas at more than one time of day when possible. Test the routes to work, school, medical care, groceries, the airport or recreation that matter to your household.
Compare the home and the location separately. A strong house in the wrong setting is still the wrong purchase. For relocation buyers, a scouting visit can be used to calibrate neighborhoods and property types even when the final home is not yet listed.
When you write an offer: build a property-specific calendar
An accepted offer creates the controlling timeline. Your broker should identify each contractual deadline and responsibility, including earnest money, inspections, financing, appraisal, title review, document delivery, closing and possession. Do not borrow a deadline from a friend’s transaction or assume an online “standard” applies.
Before signing, understand which investigations you expect to complete and whether the proposed schedule gives the relevant professionals enough time. A rural property may require well, septic, water-right, access or land-use work beyond a general home inspection. A city property may justify a sewer scope, roof review, permit research or radon test. A condo or planned community adds governing documents, budgets and association responsibilities.
Immediately after acceptance: start the parallel workstreams
Several tracks begin at once. Keep one written calendar and confirm who owns each task.
- Escrow and title: deliver funds and information only through verified instructions and review the preliminary title information with the appropriate professionals.
- Loan: complete the formal application steps, respond promptly to document requests and confirm the lender has the signed contract and property details.
- Inspection: schedule the general inspection and any specialist work early enough to receive, understand and act on the results before the contract deadline.
- Insurance: start property-specific quoting early. Roof condition, wildfire exposure, electrical systems and other features can affect availability and terms.
- Property records: gather relevant permits, HOA documents, private-road agreements, well or septic records and other material tied to the property type.
Due diligence: investigate the home you are actually buying
A general inspection is important, but it does not answer every purchase question. It is a visual review with defined limits. Use the findings to decide whether a qualified roofer, electrician, structural professional, sewer contractor, well professional, septic specialist or another expert should evaluate a concern.
The goal is not to demand that every observation disappear. Separate safety or structural issues, specialist questions, near-term capital work and routine maintenance. Then decide which findings change your willingness to proceed, your budget or the response you want to discuss with the seller.
For a more detailed framework, see our Bend home-inspection guide. Buyers considering acreage should also review our guides to shared wells and rural access and road maintenance.
Financing and appraisal continue while inspections happen
The lender’s work does not pause while you inspect the property. Continue providing requested documents, choose the loan you intend to proceed with and track the conditions that must be satisfied before closing.
The appraisal and the home inspection serve different purposes. The appraisal supports the lender’s collateral and valuation analysis; it is not a substitute for buyer due diligence or a guarantee of condition. If an appraisal issue, repair requirement or loan condition appears, ask the lender and your broker how it affects the contract and schedule.
For most covered mortgages, federal rules require the lender to provide a Loan Estimate no later than three business days after receiving a complete application. Keep the Loan Estimate for the loan you select so you can compare it with the final Closing Disclosure.
Review title, association and property documents before the deadline
Read documents when they arrive rather than saving them for the final week. Depending on the property, the file may include title exceptions, easements, CC&Rs, HOA financial material, private-road maintenance terms, well agreements or other obligations that continue after closing.
A physical inspection cannot tell you whether you may keep an RV, operate a short-term rental, build an addition or share a road or well under terms that fit your plans. Match each document to the intended use you defined at the start.
Obtain insurance and finalize the loan
Choose an insurance policy based on the specific home and the lender’s requirements. Do not rely on a portal estimate or assume coverage will match your current property. Our Bend home-insurance guide covers the property questions to raise with an insurance professional.
As closing approaches, avoid financial surprises. Keep responding to the lender, verify the source and transfer method for required funds, and ask before making employment, credit or account changes that could affect underwriting.
Three business days before a mortgage closing: review the Closing Disclosure
For covered mortgage transactions, the lender must provide the Closing Disclosure at least three business days before the scheduled closing. Compare it with the Loan Estimate and review the interest rate, loan terms, monthly payment, cash to close and itemized costs. Ask about differences while there is still time to resolve them.
Treat wiring instructions as a fraud-sensitive step. Independently verify instructions using a trusted phone number for the escrow or title company; do not rely solely on contact information in an unexpected email.
Final walkthrough, signing, recording and possession
The final walkthrough is a last condition check, not a new home inspection. Confirm that the property’s condition and any agreed work align with the contract. Raise a problem immediately rather than assuming it can be fixed after signing.
Closing can involve signing loan and transfer documents, sending verified funds, satisfying remaining conditions and recording the deed. Keys and possession follow the contract and confirmed closing process; they should not be assumed merely because documents have been signed.
A Bend buyer’s timeline checklist
- Define intended use, location needs and acceptable tradeoffs.
- Build a complete ownership budget and prepare financing.
- Tour areas through the lens of your real daily routine.
- Before offering, identify the investigations this property will require.
- After acceptance, calendar every contract and lender deadline.
- Run inspection, specialist, insurance, title and loan work in parallel.
- Read property and association documents as soon as they arrive.
- Compare the Closing Disclosure with the selected Loan Estimate.
- Verify wire instructions independently.
- Complete the final walkthrough and confirm recording and possession.
Primary sources
The Consumer Financial Protection Bureau provides a current home-buying and mortgage toolkit, a Closing Disclosure explainer and a closing-process guide. Oregon licenses and regulates real-estate brokers and escrow agents through the Oregon Real Estate Agency.
This guide is general educational information, not legal, lending, tax, title, insurance or inspection advice. The signed contract and the advice of the appropriate licensed professionals control a specific transaction.
Talk with David & the Bend Relo team
Buying, selling, relocating, or evaluating a specific property? Tell us what you are working through. We are happy to help.