

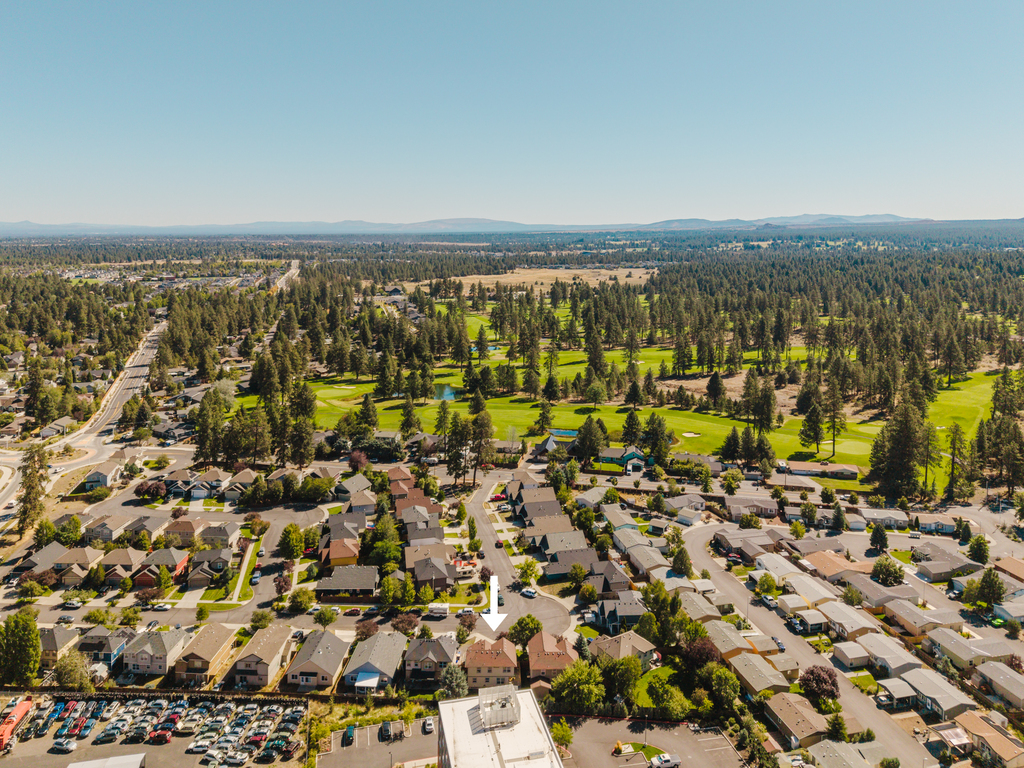
A flood-zone label is not a verdict on a Central Oregon property. It is one layer of due diligence that can affect financing, insurance, future improvements and the questions you should ask before closing. The useful question is not simply, “Is this home in a flood zone?” It is: Which mapped zone applies to the parcel and structure, what does the lender require, and what physical water risks are visible beyond the map?
That distinction matters around the Deschutes River, Little Deschutes River, Whychus Creek, Crooked River, canals, drainage corridors and low-lying rural areas. Two nearby properties can have different mapped conditions, and a parcel boundary can cross more than one zone.
Start With the Official FEMA Map
The FEMA Flood Map Service Center is the official public source for National Flood Insurance Program flood-hazard maps. Search the property address, confirm the map panel and effective date, and look at where the building footprint sits—not just the pin or parcel center.
FEMA defines a Special Flood Hazard Area, or SFHA, as land with at least a 1% chance of flooding in any given year. This is often called the “100-year floodplain,” but that phrase does not mean a flood happens only once every 100 years. Zones beginning with A, including Zone AE, generally fall within the SFHA. Zone X may represent moderate or minimal mapped hazard, depending on whether it is shaded, but it does not mean zero risk.
Maps also change. Always use the current effective product rather than relying on an old listing, a prior owner’s recollection or a screenshot saved years ago.
Use Local Maps as a Second Screen
For Deschutes County properties, the county’s DIAL property-information system and FEMA 100-year floodplain layer can help connect tax-lot information with local mapping. These are useful screening tools, but the county itself cautions that its online maps are visual aids rather than guarantees. Use the FEMA map and the appropriate local planning office to confirm what governs a specific property.
Jurisdiction matters. A Bend mailing address can be inside the City of Bend, in unincorporated Deschutes County or in another local jurisdiction. Oregon’s Department of Land Conservation and Development explains that cities and counties adopt floodplain regulations and issue floodplain-development permits locally. Ask the office with authority over the parcel—not whichever office happens to be closest.
What the Flood Zone Can Affect
Financing and flood insurance
A lender may require flood insurance when a financed structure is in an SFHA. The exact requirement depends on the loan, lender and property. Some lenders may also require coverage outside a high-risk zone. Ask the lender to order or review its flood determination early enough that the result does not surprise you near closing.
Standard homeowners insurance usually does not cover flood damage. Oregon’s Division of Financial Regulation advises consumers to discuss separate flood coverage available through the National Flood Insurance Program or private insurers. Get property-specific quotes before your insurance and financing deadlines. Do not assume the current owner’s premium will transfer or predict your cost.
Repairs, additions and rebuilding
Floodplain rules can shape where and how you add square footage, replace a structure, place fill, alter drainage or rebuild after major damage. A mapped floodway can carry different constraints from the broader floodplain. Before treating an ADU, garage, shop, addition or landscape project as feasible, talk with the local floodplain administrator and the professionals who would design or permit the work.
Resale and ownership decisions
Flood information can affect a future buyer’s lender, insurance options and improvement plans. It should be evaluated alongside access, wells, septic, wildfire exposure, easements and other property-specific issues—not treated as an automatic deal-breaker or ignored because the home has never flooded.
A Practical Flood-Risk Checklist for Buyers
- Confirm the exact property. Match the address to the tax lot and verify that the map pin is not landing on a neighboring parcel.
- Review the FEMA panel. Note the effective date, flood-zone designation, mapped floodway and any base-flood-elevation information shown.
- Locate the improvements. Determine whether the home, garage, well, septic components, driveway or planned building area intersects the mapped hazard—not merely whether any corner of the parcel does.
- Ask the lender early. Request the flood determination and written insurance requirements while your financing contingency is still useful.
- Obtain insurance quotes. Compare coverage, deductibles, limits, waiting periods and whether contents are covered. Keep flood and water-backup coverage questions separate.
- Review records. Look at seller disclosures, permits, prior surveys, elevation certificates if available, repair documentation and visible drainage work. A missing record is a reason to investigate, not proof of a problem.
- Inspect site conditions. Ask the inspector to look for drainage patterns, staining, sump systems, crawlspace moisture, grading and water entry. For complex sites, bring in a surveyor, engineer, drainage contractor or other qualified specialist.
- Check the intended use. If your plan involves an addition, outbuilding, major landscaping or redevelopment, verify floodplain and land-use requirements before relying on that plan.
This is the same property-first approach we recommend for other technical issues: start with what you want to do, identify the rules and physical systems that control it, and deepen the due diligence as the property becomes more complex. Our Bend home-inspection guide and home-insurance guide for Bend buyers provide useful companion checklists.
What If the Map and the Property Do Not Seem to Match?
Do not try to settle a boundary question by eyeballing an online layer. Map scale, parcel geometry and structure location can make a screen view misleading. Ask the lender which determination it is using, then consult the local floodplain administrator and a licensed surveyor or engineer if the result affects your purchase. FEMA has formal map-amendment and map-revision processes, but they require property-specific evidence and should not be treated as a quick workaround.
Flood Zone Is One Part of the Decision
A home outside the SFHA can still experience surface-water, drainage, groundwater or other water problems. A home inside a mapped flood zone may have documented elevation, mitigation and insurability that can be evaluated. The goal is not to generalize from a zone label; it is to understand the specific home, site, insurance and improvement constraints before you commit.
If you are comparing Bend or Central Oregon properties with floodplain, riverfront or rural-site questions, the Bend Relo team can help organize the property research and connect the right lender, insurer and technical specialists. We will not guess when a government map or licensed professional should answer the question.
Talk with David & the Bend Relo team
Buying, selling, relocating, or evaluating a specific property? Tell us what you are working through. We are happy to help.





